Principal®
Principal Financial Group, Inc.FinanceVerified
- 2.32K Reviews
- 4.7
- Downloads
- 1,000,000+
- Price
- Free
Screenshots
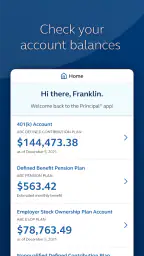
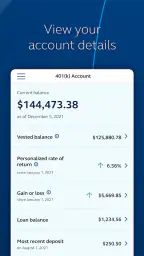
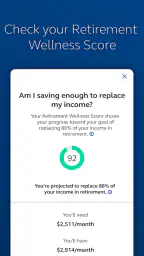
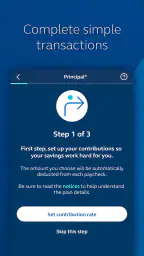
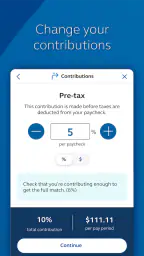
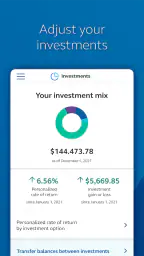
 Analysis by Appwesome
Managing money from a phone sounds simple until a task depends on a secure connection, a current account view, and a few quiet minutes to make a careful decision. I spent time with Principal® in that kind of everyday setting, treating it as a mobile finance app rather than just another account shortcut. Its purpose is clear: help you keep track of financial goals while you are away from a desktop. The experience is strongest when your phone has a reliable network and you already know what you want to check or do.
Principal Financial Group, Inc. develops the app, which is free and available to everyone by its age rating. It has been around since March 2019, and the current release is version 4.0.146. The app has built a substantial audience, with over a million installs, a 4.7 average from around forty-four thousand ratings, and roughly two thousand reviews. Those figures suggest that the product has become a familiar mobile entry point for people connected with Principal, although popularity alone does not make it the right financial tool for every person.
How connectivity shapes the everyday experience
Network-dependent moments are the real test
The most important thing to understand is that the useful part of a finance app happens when it can reach current account information securely. Opening the app is not the same as having a usable financial overview. When the connection is good, checking progress or reviewing a goal feels appropriately direct. When the network is weak, the experience becomes less predictable because financial information is not something I want to interpret from an old screen or incomplete loading state.
I noticed that this makes the app feel different from a notes app or a basic budgeting calculator. Those tools can remain useful while a phone is temporarily disconnected. Principal® is more dependent on the moment when its information can be refreshed. That is sensible for a service dealing with personal finances, but it changes how I plan to use it: I open it when I have enough signal to wait for a proper account view, not as a casual offline reference.
A realistic example is checking a financial goal while standing in a shop. If I am deciding whether a purchase fits my wider plan, I need the app to load before the decision is useful. A strong connection makes that quick enough to be practical. A poor connection can turn a simple check into a delay, which is exactly when people may be tempted to guess or postpone the decision. My advice is to treat the app as a live window into your financial relationship with Principal, not as a permanently stored record.
That distinction also affects travel. In a hotel, underground station, crowded venue, or rural area, the phone may show a very different experience from the one I get at home. I would not wait until an urgent moment to discover how the app behaves on a marginal connection. If a financial task matters, I prefer to open the app earlier, while the network is stable, and review what I need before moving on.
Mobile contexts where it works best
The app makes the most sense for short, intentional sessions. I can imagine using it during a morning routine to check whether a goal still looks on course, during a lunch break to review an account-related detail, or before making a larger purchase that deserves more thought. These are small moments, but they are exactly where mobile access can make financial habits more consistent than waiting for a computer.
Other Stories to Read




It is less comfortable when I want to study a complicated financial picture for a long time. A phone screen encourages quick movement and limited comparison, while a larger display is better for laying out several figures or documents side by side. Principal® can help me stay connected to my goals, but I would not confuse that convenience with a replacement for every form of financial planning.
One useful habit is to separate checking from deciding. I can use the app on the move to see where things stand, then make a more considered decision later when I have time and a reliable connection. This reduces the risk of acting on a rushed glance. It also makes the mobile format an advantage rather than a limitation: the app keeps the goal present in daily life without forcing every financial decision into a hurried phone session.
For people who already use Principal’s services, that convenience is the main reason to try it. The app brings financial goals into the same device used for calendars, messages, and shopping decisions. That proximity can be valuable because a goal is easier to remember when checking it takes a short, deliberate action. On the other hand, someone looking for a broad, all-in-one view of accounts from many unrelated providers may find a provider-specific app narrower than a general finance dashboard.
What happens when a connection fails
Connectivity problems are not just an inconvenience in this category. A failed load can leave me unsure whether I am looking at current information, whether a request went through, or whether I should try again. I would be cautious about repeatedly tapping a control after a timeout, especially if the action might affect an account or goal. The safer workflow is to pause, check whether the screen gives a clear result, and reconnect before attempting anything important again.
That is one of the app’s practical weaknesses from a user perspective: a mobile finance experience needs to make uncertainty feel manageable. If the network drops during a routine review, I can simply wait and retry. If it happens while I am trying to complete a meaningful account action, I want a clear confirmation before assuming success. I would always verify the resulting account view rather than relying on the fact that a button appeared to respond.
Recovery is easier when I use a simple sequence. First, I check whether other apps can reach the internet, which tells me whether the problem is local to the connection. Next, I return to the app without repeatedly submitting the same request. Then I reload the relevant view once the signal is steady. If the issue continues, I move the task to a more dependable connection or use another official route rather than improvising.
This is also where expectations matter. A finance app should not be judged by whether it works like an offline calculator. Its job involves current information, so the network requirement has a reasonable purpose. Still, the trade-off is real: people who regularly work in places with unstable service may experience more friction than users with dependable home and mobile connections.
Using it carefully on mobile data
I would not describe normal financial checking as a reason to avoid mobile data, but I would still use it thoughtfully. The important issue is not only how much data a session consumes. It is also whether a refresh happens at a convenient time, whether the screen loads completely, and whether I have enough battery and signal to finish what I started. A quick check before leaving a trusted connection can prevent unnecessary retries later.
For data-conscious use, I would avoid repeatedly opening and closing the app simply out of curiosity. Instead, I would decide what I want to review first, open it once, and allow the relevant information to load. If the connection is poor, repeated attempts may create frustration without producing a better answer. This is a small behavioral change, but it makes the experience calmer and more efficient.
People with limited data plans should also distinguish between a brief status check and a longer session involving multiple screens. I would do detailed reviewing over a dependable Wi-Fi connection when possible, especially if I am already planning a financial task rather than merely checking progress. That is not because the app is unsuitable for mobile networks; it is because financial attention is easier to maintain when the connection is stable and the phone is not constantly struggling to refresh.
Another practical tip is to avoid making a rushed decision simply because a screen loads slowly. Slow connectivity can create a false sense of urgency: I may want to finish before the signal disappears, even though the financial choice deserves more time. If the app cannot present a clear, current view, I would postpone the decision until the connection improves. That is a better habit than treating a partially responsive session as good enough.
Who will get the most from it
I think the app is best suited to people who already have a relationship with Principal and want a convenient mobile way to stay aware of their financial goals. It is particularly useful for someone who checks progress in short intervals, travels between reliable and unreliable connections, or wants to make financial awareness part of an ordinary routine. The free price removes a barrier to trying it, and the Everyone rating makes it broadly approachable from an access standpoint.
It may also suit a person who tends to ignore long-term goals when they are hidden behind a desktop login. A phone-based check can create a useful prompt to look again. The value is not that the app magically improves a financial plan; it is that it reduces the distance between the user and the information needed to stay engaged with that plan.
I would be more cautious about recommending it as the only finance app for someone whose main need is household budgeting across unrelated banks, cards, bills, and investments. A provider’s own app is usually more focused on its relationship with you, while a general budgeting service may be better for combining an entire financial life in one place. Likewise, anyone who needs a large-screen planning workspace may prefer a browser or desktop experience for deeper reviews.
It is also not the right choice for someone who expects every finance tool to remain fully useful without a connection. The app’s central value depends on reaching current information, so a person who spends much of the day offline should plan around that limitation. I would still consider installing it if Principal is important to them, but I would not promise that it will function like a standalone record when the network is unavailable.
How it compares with usual alternatives
Compared with visiting a website in a mobile browser, a dedicated app feels more natural for repeated checks. I do not have to begin each session by finding the right page, and the experience is built around the phone rather than a general browsing window. The trade-off is that the app is another installed tool to maintain, and it remains tied to Principal rather than acting as a neutral place for every financial provider.
Compared with a spreadsheet, the app is better for checking current information connected to Principal, while a spreadsheet is better for custom calculations, personal categories, and long-term scenarios that I design myself. I would use a spreadsheet to model possibilities and the app to stay connected to the actual relationship. Trying to force one tool to do both jobs can make either feel inadequate.
Compared with a broad budgeting app, Principal® offers a more focused experience. That focus can reduce clutter when I only need to review Principal-related goals. It can also feel limiting when I want a complete household picture. The better choice depends on whether my priority is depth with one provider or breadth across many accounts.
Compared with doing nothing until a monthly desktop review, the mobile app has a clear behavioral advantage. Short checks can keep a goal visible between larger planning sessions. However, frequent access is not automatically better. If I only open it to worry over small changes or make impulsive decisions, the convenience works against me. I get the most value when each visit answers a specific question.
Small workflows that improve the experience
My first recommended workflow is a “before you leave” check. While connected to a dependable network, I review the goal or account information I expect to need during the day. This does not create an offline version of the app, but it gives me a clearer starting point and reduces the temptation to make a decision from memory when I am away from reliable service.
The second is a confirmation habit after any interrupted session. If the network fails, I do not assume that an action completed merely because the screen changed. I wait for a stable connection and verify the account view. That extra moment is especially worthwhile in a finance app, where uncertainty is more serious than the inconvenience of trying again.
The third is to use the app as a checkpoint rather than a complete financial plan. I might check progress after receiving income, before a planned purchase, or during a regular weekly review. Then I record the broader decision elsewhere if I need detailed comparisons. This division keeps the mobile experience quick while preserving room for thoughtful planning.
A fourth insight is that connectivity should influence timing, not just troubleshooting. If I know I will be travelling through areas with weak service, I can handle important reviews before departure. If I am about to make a significant decision, I can wait until I am settled rather than checking hurriedly in a crowded or moving environment. The app becomes more dependable when I choose the right moment to use it.
My connectivity verdict
Principal® succeeds as a focused mobile finance companion for people who want to stay close to their Principal-related financial goals. I like the way it fits short, purposeful checks into ordinary life, and the strong user response suggests that many people find that role useful. Its free availability and established presence make it easy to consider if you already use the developer’s services.
My reservation is not about the idea of mobile access; it is about the unavoidable dependence on a working connection for current financial information. Weak signal, interrupted loading, or uncertainty after a failed request can make an otherwise simple task feel more serious. The app is best used with a stable network, a clear intention, and a willingness to verify rather than guess.
In the end, I would recommend it to an existing Principal customer who wants convenient goal awareness without turning every check into a desktop session. I would pair it with a broader budgeting or planning method if my finances span several providers, and I would choose a browser or larger screen for detailed work. Used within those boundaries, it is a practical way to keep financial goals present while moving through the day.
Highlights
- Simple interface makes daily task management quick to learn.
- Useful reminders help keep important activities from being forgotten.
- Supports better organization of routines and personal priorities.
- Lightweight design should run smoothly on many modern devices.
- Suitable for users seeking a focused productivity experience.
Limitations
- Some advanced planning tools may be limited compared with larger suites.
- The app may require regular notification access to work as intended.
- Customization options could feel basic for power users.
- Users may need time to configure routines and preferences properly.
- Feature availability may vary between Android and iOS versions.
Frequently Asked Questions
01What is Principal® and what can I use it for?
Principal® is a financial planning and investment app designed to help users manage money, review financial products, and monitor progress toward long-term goals. Depending on your location and the services available for your account, you may be able to view balances, track investments, explore retirement options, review insurance information, or contact a financial professional. Features can vary by country, account type, and eligibility.
02Is Principal® free to download and use?
The Principal® app is generally available to download without an upfront purchase price, but downloading the app does not mean that every service is free. Some investment, retirement, insurance, or advisory products may include management fees, fund expenses, transaction costs, or other charges. Before opening an account or making a financial decision, carefully review the applicable product documents, fee schedules, and service terms.
03Can I use Principal® to manage my retirement or investment accounts?
If your employer, financial provider, or account is supported, Principal® can allow you to review retirement and investment information from a mobile device. Common tools may include checking balances, viewing contributions, examining performance, changing selected settings, and accessing educational resources. Available actions depend on the specific plan and permissions, so the app may offer viewing access for some accounts but not full management.
04Is my personal and financial information secure in Principal®?
Principal® uses account authentication and security measures intended to protect personal and financial information, but no online service can guarantee that risks are completely eliminated. Use a strong, unique password, enable available biometric or multi-factor security options, keep your device updated, and avoid signing in over unsecured public networks. Never share verification codes or login details with anyone claiming to represent support.
05What should I do if I cannot log in or notice an incorrect transaction?
If you cannot access Principal®, first check your internet connection, update the app, and use the official password-reset or account-recovery process rather than relying on links from messages or social media. For an unfamiliar transaction, incorrect balance, or suspected unauthorized access, contact Principal® through the official support channels as soon as possible. Keep screenshots and relevant dates available, and do not make financial decisions until the issue is clarified.


